4 Practical Imperatives for PE and Portfolio Company Leadership
“I think the financial engineering element of private equity is probably not going to be as much of a driver of returns going forward. So, it’s going to take real, organic, revenue growth … to get those returns.”
So says Jeff Mindlin, CIO at the ASU Foundation (Source: AI-CIO.com), and he seems to be on to something.
The playbook that once powered PE returns – leveraged buyouts, cost cuts, and EBITDA arbitrage – is arguably losing its pull. Today, organic growth, strategy, and execution are becoming the real competitive advantage.
Like most things, if you follow the data you’ll win, and the data helps validate Mindlin’s stance:
- Leverage’s declining role: Before 2000, financial engineering (mainly leverage) accounted for ~70% of value creation. In the post-2008 global financial crisis era, that’s decreased sharply to just 25%. (Source: CAIS Group)
- Operations rising: According to PwC, operational value creation now drives ~47% of returns – up from 18% in the 1980s – while financial engineering has retreated. (Source: PwC)
- Revenue growth is key: A 2024 study found that 46% of returns now stem from business improvement – two-thirds of which is from topline revenue growth. (Source: Simon-Kucher)
So, what can be done?…
- Prioritize revenue engines over debt plays: Cheap leverage is fading. Sustainable returns now require scalable sales strategies, demand-gen models, and customer retention frameworks.
- Emphasize RevOps as a strategic discipline: Systems that align GTM, data, and execution are no longer optional. They are mission-critical for unlocking organic growth.
- Proactively access growth in due diligence: Shockingly, only ~33% of firms evaluate sales opportunity during deal vetting. (Source: Simon-Kucher) That’s a flaw – growth potential must be built into the thesis, not added as an afterthought.
- Build operational teams – early and deep: Operating partners are now central. Investors expect them to span the entire deal lifecycle – from due diligence to exit execution.
For our part, this is a big reason why we built NorthShift™ and the A(i)scent™ platform. In today’s PE climate – with high rates, tightened leverage, and sophisticated LP expectations – organic revenue growth is no longer a “nice-to-have.” It’s a defining lever of performance, and those who harness it will rewrite the rules of value creation.
NorthShift’s mission: To provide growth-, turnaround-, and exit-stage companies with our proven experience building streamlined revenue engines and improving GTM performance through AI, and to do so without the burden of overhead or expensive full-time hires.
We believe: Any company can grow, and that building things is a joy.
We combine the power of AI with the rigor and wisdom of human experience.
We value transparency and accountability.
We create solutions with milestones, momentum, and results.
All contents are property of NorthShift Consultancy Group, LLC.
NorthShift™ and A(i)scent™ are trademarks of NorthShift Consultancy Group, LLC.
© 2025 NorthShift Consultancy Group, LLC. All rights reserved.
Recent Posts
Is The AI Analyzing Your Deals Also Exposing Them?
An examination of how AI-powered deal and portfolio tools handle confidential data during normal operation — and why the architecture of those…
The Invisible Data Problem
An examination of how the intelligence and analytics tools widely deployed across private equity portfolios handle confidential company data — and why…
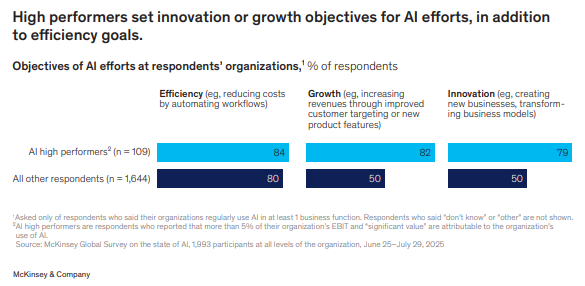
MP/GP Warning: Your LPs Don’t Care That You “Have AI.” They Care What It Changed.
LPs and boards are done funding “AI ambition.” They’re asking for proof—measurable, repeatable, auditable proof—that AI is improving the investment and execution…