In 2026, Revenue Proof – Not Hope – WIll Price Deals
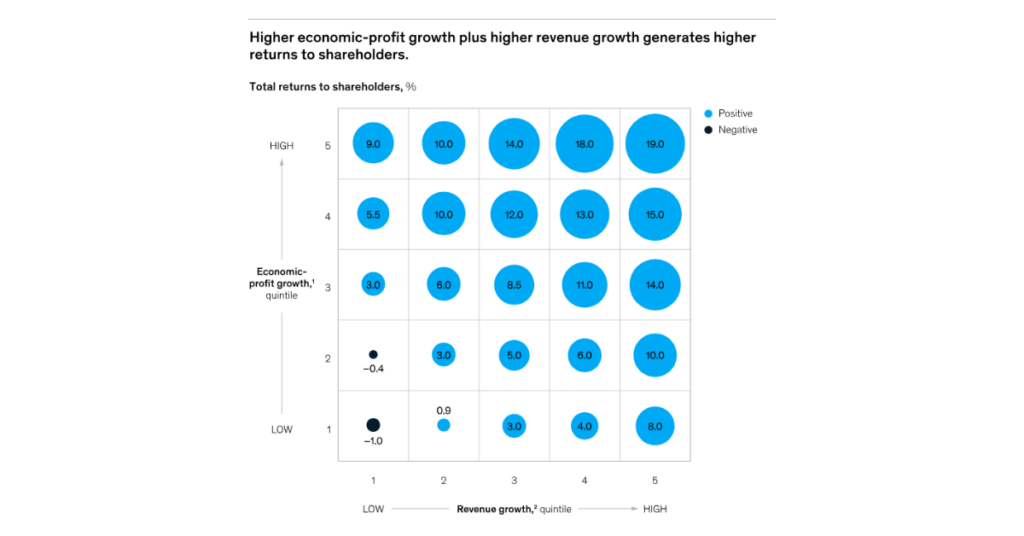
More so than ever, PE firms cannot afford to underwrite revenue growth based on portco management conviction and historical CAGR alone. Investment committees will expect instrumented proof that revenue levers can be pulled — and pulled fast.
In 2026, the GPs that embrace this early and often will be ahead of the curve.
McKinsey data already points to where this is going. Companies with similar EBITDA profiles are being valued very differently based on one factor: measured revenue momentum — pipeline conversion, retention durability, and speed-to-impact post-close.
McKinsey’s chart mapping revenue growth + economic profit against total shareholder return shows that companies that grow revenue systematically and drive profit above cost of capital deliver materially higher valuation outcomes — not just temporary multiple bumps.
This is the quiet shift happening beneath the market.
In 2026, we believe this becomes explicit.
At NorthShift, we built the A(i)scent platform to pressure-test growth assumptions against 3-statement model financial data points and conversational inputs. A(i)scent codifies the latter and algorithmically connects it to the hard numbers of the former, unlocking which revenue levers actually expand enterprise value — and the quantifiable role revenue plays in that equation.
It’s based on math, not emotion.
Prediction: The firms that can prove revenue upside before close will win 2026. Everyone else will pay for hope.
Get in touch with us to learn more.
Recent Posts
Is The AI Analyzing Your Deals Also Exposing Them?
An examination of how AI-powered deal and portfolio tools handle confidential data during normal operation — and why the architecture of those…
The Invisible Data Problem
An examination of how the intelligence and analytics tools widely deployed across private equity portfolios handle confidential company data — and why…
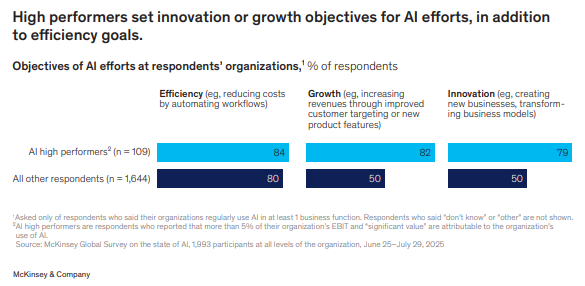
MP/GP Warning: Your LPs Don’t Care That You “Have AI.” They Care What It Changed.
LPs and boards are done funding “AI ambition.” They’re asking for proof—measurable, repeatable, auditable proof—that AI is improving the investment and execution…